
Partner with Hire Chore and focus on your strengths.
*100% free, no-obligations consultation to determine your Ops blockers

Enter your info to receive the guide instantly.
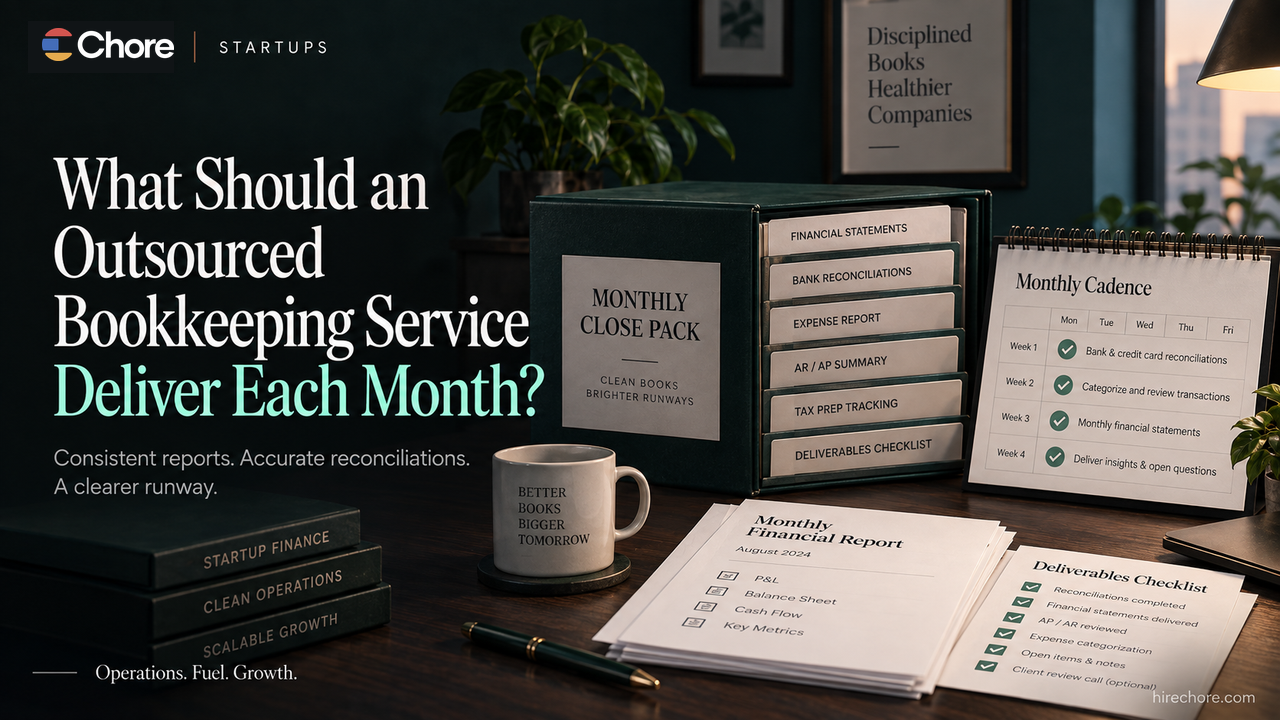
A good outsourced-bookkeeping engagement should make “done” observable.
That means the startup should know:
- what it must provide;
- what the bookkeeper must complete;
- what evidence proves the work is finished;
- when the deliverables are due;
- who reviews them;
- how exceptions are handled; and
- what is explicitly out of scope.
Receiving a profit and loss statement is not enough by itself.
A monthly service should be defined as a two-party operating agreement:
client inputs → provider work → completion evidence → delivery → review → exception / acceptance
If any part is vague, the founder is left guessing whether a late close is a provider problem, a missing-client-input problem, or a scope problem.
Start by separating client inputs from provider obligations
The monthly cycle should begin with a clear input cutoff.
For every required input, record:
- what the client must provide;
- who owns it;
- where it should be delivered;
- the cutoff date;
- what happens if it is late; and
- which provider deliverable depends on it.
Typical client inputs can include:
- bank and credit-card statements;
- payroll reports;
- expense reports;
- invoices and bills;
- loan statements;
- revenue or billing-system exports;
- equity or financing updates;
- unusual-transaction context;
- requested approvals; and
- supporting documents for unclear entries.
Do not let the provider's delivery target float independently of missing source records.
If the client sends a key bank statement five days late, the monthly service specification should show that dependency rather than simply marking the provider “late.”
Define the core monthly bookkeeping outputs
The exact package varies by company, accounting basis, entity structure, and scope.
Still, a typical core monthly package should usually address these operating jobs:
1. Transaction processing is complete
The agreed transactions for the period are posted, categorized, or otherwise accounted for under the engagement scope.
Completion evidence might include:
- cleared uncategorized-transaction queue;
- exception list;
- transaction-review report; or
- provider completion note.
2. In-scope accounts are reconciled
The books should be compared to relevant external statements and unexplained differences should be resolved or documented.
IRS Publication 583 describes reconciling the checking account and retaining supporting records, while Xero's current reconciliation guidance similarly describes comparing accounting records with external statements and investigating differences. These sources do not define a bookkeeping-service package, but they support the evidence principle behind reconciliation. (IRS Publication 583) (Xero)
For each agreed account, require:
- reconciliation period;
- ending external balance;
- ending book balance;
- unresolved difference;
- preparer;
- reviewer, if required; and
- evidence location.
3. The agreed reporting package is delivered
Do not hard-code one universal report bundle.
Depending on the engagement, the package might include:
- profit and loss statement;
- balance sheet;
- cash-flow report or cash view;
- accounts receivable aging;
- accounts payable aging;
- debt schedule;
- deferred-revenue schedule;
- prepaid-expense schedule;
- fixed-asset schedule;
- KPI or variance reporting; or
- management-specific schedules.
The SBA's current business-management guidance reinforces the basic role of bookkeeping and financial statements in understanding the business, but it does not prescribe one standard vendor package. (SBA)
So the monthly specification should say exactly which reports are included for this company.
Require completion evidence, not just deliverable names
A provider can send “P&L, balance sheet, and reconciliations” while leaving the founder unable to tell whether the work is actually complete.
Pair every deliverable with evidence.
Example:
| Deliverable | Completion evidence |
|---|---|
| Bank reconciliation | Reconciliation report or equivalent tie-out showing remaining exceptions |
| Credit-card reconciliation | Statement-to-ledger tie-out |
| P&L | Final report tied to the agreed close version |
| Balance sheet | Final report plus support for material balance-sheet accounts |
| AR aging | Current report plus unresolved / disputed-item notes where in scope |
| AP aging | Current report plus open exception notes |
| Deferred revenue schedule | Schedule tied to the relevant ledger account |
| Close summary | Open issues, assumptions, unusual items, and next actions |
| Exception list | Every unresolved item with owner and target date |
QuickBooks currently provides reconciliation reports that can show prior reconciliation detail and be exported for review. That is one product-specific example of completion evidence, not a universal standard. (QuickBooks reconciliation reports)
The operating rule is broader:
If the provider says a task is complete, the startup should know what evidence demonstrates completion.
Agree the delivery target only after defining when the clock starts
A service-level target is meaningless without an input dependency.
Instead of:
“Books delivered by the 10th.”
Use:
“Provider delivers the agreed monthly package within X business days after all required source records and approvals are available.”
Then define:
- client cutoff;
- provider start condition;
- target delivery date;
- reviewer;
- correction window;
- exception status;
- escalation point.
Do not present a market-wide close target as if every startup should use it.
Different providers, books, transaction volumes, entity structures, accounting complexity, and client-response times can justify different dates.
If a provider advertises a specific target, treat that as the provider's own commercial promise, not an industry standard.
Define what “complete” means
A useful monthly service specification should support several completion states.
COMPLETE
The agreed in-scope work is finished, evidence is available, required review is complete, and no unresolved material exception prevents acceptance.
COMPLETE WITH DOCUMENTED EXCEPTION
The main package is usable, but a defined unresolved item remains with:
- description;
- affected account or deliverable;
- owner;
- expected effect, where reasonably determinable;
- next action;
- target date; and
- disclosure / follow-up status.
WAITING ON CLIENT
The provider cannot continue because an agreed client input, approval, or explanation is missing.
The missing item should be named explicitly.
PROVIDER CORRECTION REQUIRED
The provider's work is incomplete or needs correction based on the agreed specification.
OUT OF SCOPE
The item is not part of the contracted monthly bookkeeping service and needs a different owner or separate scope.
These statuses are much more useful than a generic red / green dashboard because they explain what happens next.
Separate core bookkeeping from optional or separately contracted work
One of the biggest sources of outsourced-finance frustration is assuming that “bookkeeping” includes everything finance-related.
It often does not.
Your specification should classify services as:
- core monthly bookkeeping;
- optional / separately contracted;
- excluded / owned elsewhere.
Examples that frequently need explicit treatment include:
Accounts payable operations
Does the provider only post vendor bills, or does it also:
- collect bills;
- chase approvals;
- manage payment runs;
- maintain vendor records; or
- release payments?
Access and cash authority belong in a separate control design, not hidden in a deliverables list.
Accounts receivable operations
Does the provider only record invoices and cash, or also:
- manage billing;
- maintain the AR aging;
- send reminders;
- track disputes;
- manage promises to pay; or
- run the collections cadence?
Those are different scopes. If collections management is included, use the AR aging and collection workflow to define the recurring operating process.
Payroll
Does bookkeeping include:
- posting payroll journals;
- reconciling payroll;
- payroll processing;
- employee changes;
- tax deposits;
- quarterly returns; or
- W-2 preparation?
Never assume the whole chain is included.
Tax work
Bookkeeping and tax filing are separate services unless explicitly combined.
Classify:
- sales tax;
- income-tax work;
- payroll-tax returns;
- 1099s;
- franchise taxes;
- state filings; and
- tax notices
as separate scope items unless the contract says otherwise.
Controller / CFO work
Do not treat:
- technical accounting judgments;
- board reporting;
- cash forecasting;
- budgeting;
- strategic finance;
- financing models;
- investor reporting;
- policy decisions; or
- audit support
as automatically included in routine bookkeeping.
The clearer this boundary is, the easier it is to evaluate the provider fairly.
Name the reviewer and acceptance process
Someone on the company side should own acceptance.
That may be:
- founder;
- finance lead;
- controller;
- chief of staff;
- outsourced controller; or
- another authorized reviewer.
For every monthly package, the reviewer should know:
- what was due;
- what arrived;
- what evidence supports it;
- what remains open;
- whether any item is waiting on the client;
- whether a correction is required; and
- whether the period can be accepted.
Avoid self-approval for consequential accounting judgments where an appropriate independent review is needed.
The monthly package should not silently move from “provider sent files” to “company accepted the books.”
Use one Monthly Delivery Specification
The easiest way to make the engagement reviewable is to keep one matrix.
Recommended fields:
| Field | What to record |
|---|---|
| Deliverable | Exact output or task |
| Client input | What the provider needs from the company |
| Input owner | Person responsible for providing it |
| Input cutoff | When it is due |
| Provider task | Work the provider performs |
| Completion evidence | What proves the task is complete |
| Delivery target | Agreed timing after dependencies are met |
| Reviewer | Who evaluates the deliverable |
| Acceptance status | Complete / exception / waiting / correction / out of scope |
| Exception owner | Person responsible for unresolved item |
| Escalation deadline | When unresolved item must be escalated |
| Scope classification | Core / optional / excluded |
| Notes | Assumptions or special conditions |
This matrix should sit next to the contract or statement of work.
The contract may define legal obligations. The matrix makes those obligations operational.
A practical monthly deliverables matrix
Use this as a starting point, then tailor it to the actual engagement.
| Deliverable | Client input | Provider task | Completion evidence | Scope |
|---|---|---|---|---|
| Transaction processing | Statements, receipts, explanations | Post / categorize agreed transactions | Cleared queue + exception list | Core |
| Bank reconciliations | Complete bank statements / feeds | Reconcile in-scope accounts | Reconciliation report / tie-out | Core |
| Credit-card reconciliations | Card statements | Reconcile in-scope cards | Reconciliation report / tie-out | Core |
| P&L | Completed close data | Produce final agreed report | Final report version | Core |
| Balance sheet | Completed close data | Produce final agreed report | Final report + support for material accounts | Core |
| AR aging | Billing / customer data | Produce aging and agreed notes | Aging report + exceptions | Core or optional |
| AP aging | Vendor / bill data | Produce aging and agreed notes | Aging report + exceptions | Core or optional |
| Debt schedule | Lender statements | Update schedule | Schedule tied to ledger | Optional |
| KPI / variance report | Agreed metrics / budget | Produce agreed analysis | Final report + assumptions | Optional |
| Payroll posting | Payroll reports | Record / reconcile payroll journals | Payroll-to-ledger tie-out | Optional |
| Tax filings | Tax data | File returns / remit taxes | Filing / payment evidence | Separate unless contracted |
| Forecasting / budgeting | Operating assumptions | Build / update model | Reviewed forecast | Separate controller / CFO scope |
| Payment execution | Approved bills / authority | Release cash if authorized | Payment confirmation | Separate control decision |
Do not copy the matrix blindly. The entire point is to make the real engagement explicit.
Handle incomplete months transparently
A monthly close should not become “complete” because the calendar advanced.
If the provider is waiting on client inputs, record:
- missing item;
- owner;
- requested date;
- effect on deliverables;
- revised target;
- next follow-up.
If the provider has an unresolved accounting question, record:
- issue;
- account / report affected;
- technical owner;
- evidence needed;
- target decision date;
- whether the package can be accepted with the issue open.
If something is outside scope, do not let it disappear into “pending.”
Assign the correct owner.
Review the engagement, not just the month
The specification is also a provider-review tool.
Every quarter or periodically, ask:
- Which client inputs are consistently late?
- Which deliverables are consistently late?
- Which reconciliations repeatedly carry exceptions?
- Which “optional” tasks are actually happening every month?
- Which out-of-scope items keep surprising the team?
- Which reports are never used?
- Which reports are missing?
- Are response and correction times acceptable?
- Are the reviewer and escalation owner still correct?
- Does the service scope still match the company's complexity?
This lets you distinguish:
- a bad provider;
- a bad scope;
- bad client inputs;
- unclear ownership; or
- a company that has outgrown basic bookkeeping.
Keep access controls separate
This article defines what the provider should deliver.
It should not also define who can access the bank, create vendors, approve bills, release cash, or hold administrator rights.
Those controls deserve their own design.
Use the outsourced-bookkeeping access and approvals framework for:
- system permissions;
- cash authority;
- payment approval;
- role separation;
- audit logs;
- credential ownership; and
- offboarding.
Separating these jobs prevents a service specification from quietly granting operational authority.
Keep the detailed close process separate too
The provider's monthly deliverables and the actual close workflow are related, but they are not identical.
If you need the procedural sequence for reconciling and closing the books, use Chore's month-end close checklist.
If you need pricing benchmarks or cost-by-scope comparisons, keep that discussion in the dedicated outsourced-accounting-cost content rather than turning this page into a pricing guide.
If you are still deciding which finance functions to outsource, use Chore's guide to outsourcing startup financial management.
Where Chore fits
Chore's current bookkeeping product page describes startup bookkeeping and monthly-close work, including reconciliations, schedules, financial statements, dashboards, and a provider-specific delivery target. Those are useful examples of one provider's current package, not an industry standard. (Chore bookkeeping and finance)
Before relying on any provider, including Chore, compare its live scope against the same Monthly Delivery Specification:
- What exactly is included?
- What does the client need to provide?
- When does the delivery clock start?
- What evidence is delivered?
- Who reviews the package?
- What happens when an input is late?
- What happens when a reconciliation does not tie?
- Which services are optional?
- Which services are explicitly excluded?
- What requires a separate controller, CPA, payroll, tax, or legal owner?
A good outsourced bookkeeping engagement should not require the founder to guess whether the month is done.
The scope, evidence, timing, exceptions, and acceptance should make that answer visible.

The Chore team consists of individuals from diverse backgrounds with a passion for learning and a desire to share knowledge.
Chore's content, held to rigorous standards, is for informational purposes only. Please consult a professional for specific advice in legal, accounting, or other expert areas.